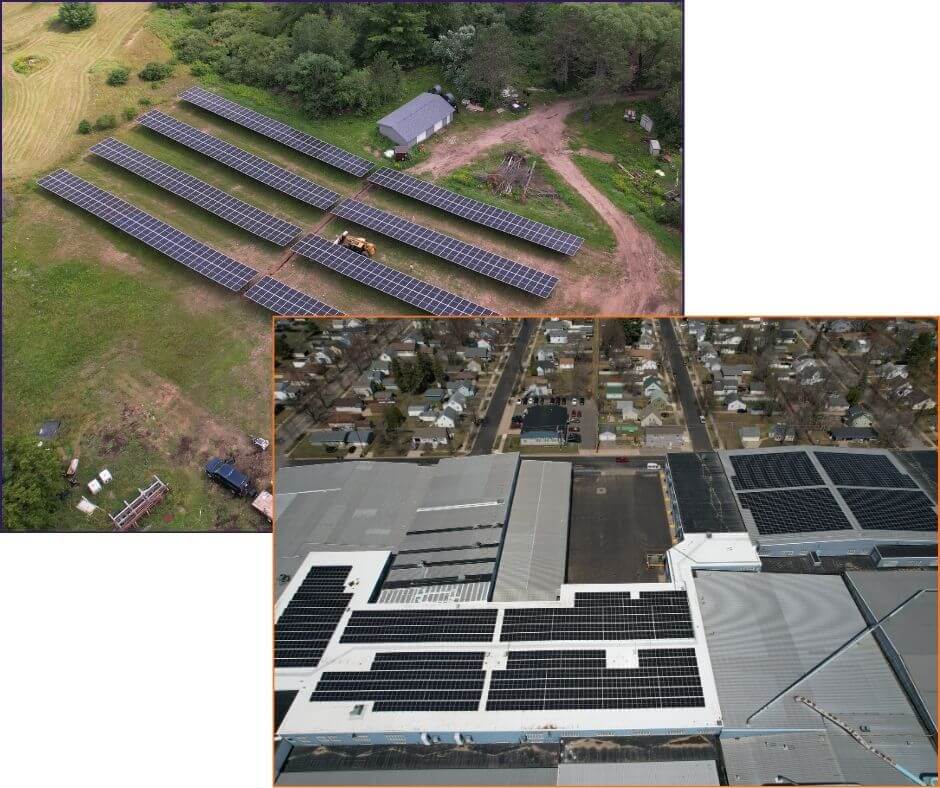
Solar has a firm end date. The 2025 law (Public Law 119-21) ends the clean electricity investment credit (Section 48E) for solar placed in service after December 31, 2027, unless construction began by July 4, 2026. That start date has passed. If you are planning a project now, assume it must be running by the end of 2027 to earn the credit. The IRS lists a 6% base credit that rises to 30% for projects meeting prevailing-wage and apprenticeship rules, plus possible bonuses for domestic content and energy communities. Projects under 1 MW (AC), which includes most business, farm and school systems, generally get the 30% rate without the wage and apprenticeship rules; confirm with your tax advisor.
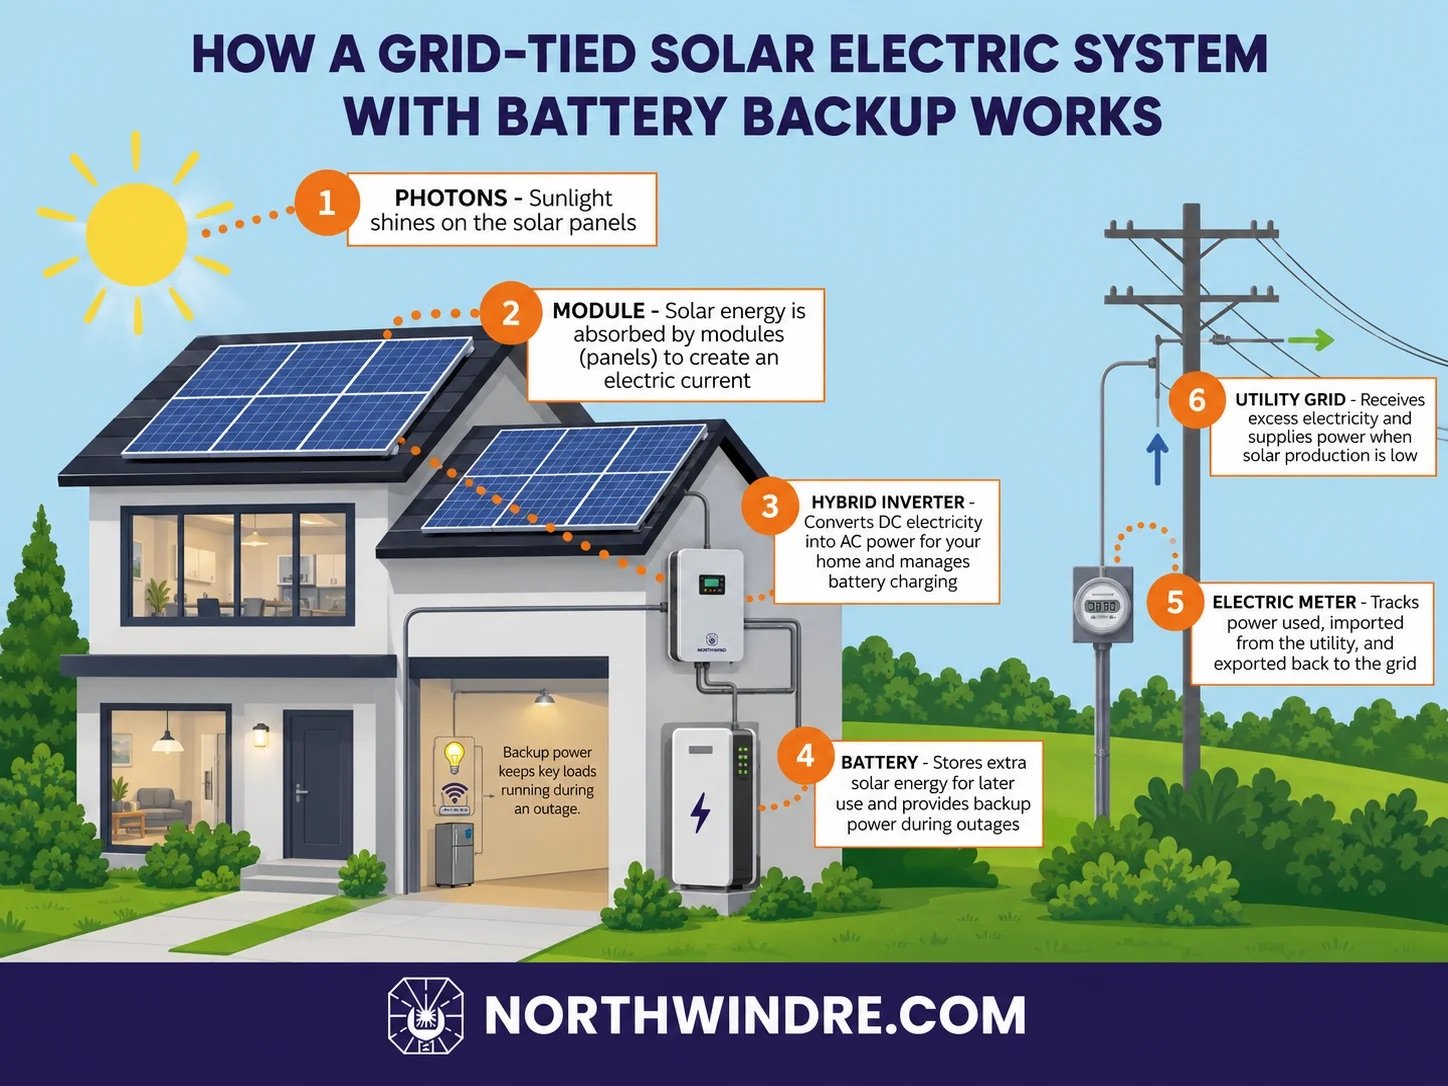
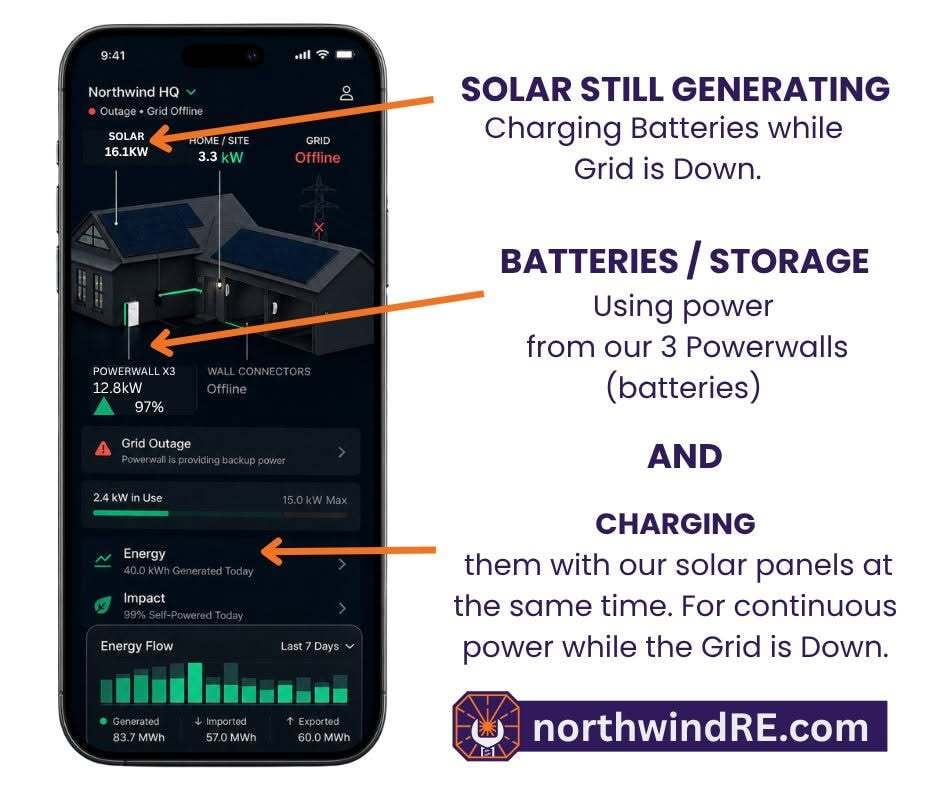
Batteries have more time. Energy storage is carved out of the 2027 solar cutoff, so a battery can still earn the 48E credit after 2027. Under current law, the storage credit runs into the 2030s.
Foreign supplier rules. Solar and storage projects that begin construction after December 31, 2025 can lose the credit if too much of their equipment cost comes from a "prohibited foreign entity." For batteries starting in 2026, at least 55% of the counted cost must come from other sources (IRS Notice 2026-15). Ask for supplier certifications in writing.
Depreciation. The same law made 100% first-year bonus depreciation permanent for qualified property acquired after January 19, 2025.
Nonprofits and governments can receive certain clean energy credits as a payment through IRS elective pay.
In June 2026 a federal court vacated the IRS notice that narrowed what counts as "beginning construction"; the government could still appeal. The July 4, 2026 / December 31, 2027 dates are in the statute itself. Confirm every deadline and credit amount with your tax advisor before you sign. See our commercial solar page.